Written and fact-checked by Waseem Aijaz, WordPress Developer & SEO Expert.
Quick answer: UK pension tax relief gives you back the Income Tax you’d otherwise pay on money you put into your pension — 20% for basic rate taxpayers, 40% for higher rate, and 45% for additional rate (42%/45%/48% in Scotland). Basic rate relief is automatic. Anything above that, in most cases, you have to actively claim.
Why Pension Tax Relief Exists
The idea is simple, even if the mechanics aren’t: the government doesn’t want to tax you twice on money that’s going toward your retirement. So when you put £100 into your pension, the taxman effectively hands some of that £100 back — because you’d already have paid Income Tax on it if it had landed in your bank account instead.
The tricky part isn’t the concept. It’s that how much comes back, and how it comes back, depends entirely on your tax band and your contribution method — and that’s where most people either underestimate what they’re owed, or assume it’s all handled automatically when it isn’t.
How Much Pension Tax Relief Do You Get, By Band?
| Your Income Tax band | Relief you’re entitled to | Is it automatic? |
|---|---|---|
| Basic rate (up to £50,270) | 20% | ✅ Yes, applied automatically |
| Higher rate (£50,271–£125,140) | 40% | ⚠️ 20% automatic, 20% must be claimed |
| Additional rate (over £125,140) | 45% | ⚠️ 20% automatic, 25% must be claimed |
| Scottish Basic/Intermediate | 20–21% | ✅ Mostly automatic |
| Scottish Higher/Advanced/Top | 42–48% | ⚠️ 20% automatic, rest must be claimed |
If you only remember one line from this article, make it this one: relief above the basic rate is not paid into your pension automatically in most cases. It either comes to you as a bigger tax code adjustment, a Self Assessment refund, or — if nobody claims it — it simply doesn’t happen.
A Real Example: £55,000 Salary, 8% Pension Contribution
Say you earn £55,000 a year and contribute 8% of your salary — £4,400 — into your pension.
What Happens Automatically
You’re a higher rate taxpayer, since your income is above £50,270. Your pension provider automatically claims 20% relief on your contribution, so your £4,400 actually only “cost” you £3,520 out of your take-home pay.
What You Have to Claim Yourself
You’re entitled to 40% relief in total. The extra 20% — roughly £880 in this example — isn’t added automatically. You need to declare your pension contributions on a Self Assessment tax return, or contact HMRC directly, to get it back as a tax refund or a tax code adjustment.
That’s £880 a year that a lot of higher rate taxpayers simply never claim, year after year, without realising it’s sitting there.
How to Claim the Extra Relief You’re Owed
- Check your contribution method first. If your employer uses salary sacrifice or a net pay arrangement, you may already be getting full relief automatically through payroll — in that case, there’s nothing extra to claim. It’s specifically relief-at-source personal contributions where the gap usually appears.
- Fill in the pension contributions section of your Self Assessment tax return, if you already complete one.
- If you don’t do Self Assessment, you can write to HMRC or use their online service to claim the relief directly — you don’t need to start filing a full tax return just for this.
- Keep your pension contribution statements. You’ll need the total gross amount contributed for the tax year, which your provider can confirm.
Relief at Source vs Net Pay Arrangement vs Salary Sacrifice
Not all workplace pensions handle relief the same way, and this is where a lot of confusion starts.
| Method | How relief is applied | Do you need to claim anything? |
|---|---|---|
| Relief at source | Provider adds 20% automatically; you claim the rest if you’re above basic rate | Yes, if you’re a higher/additional rate taxpayer |
| Net pay arrangement | Contribution comes out of your salary before tax is calculated | No — full relief is automatic at your actual rate |
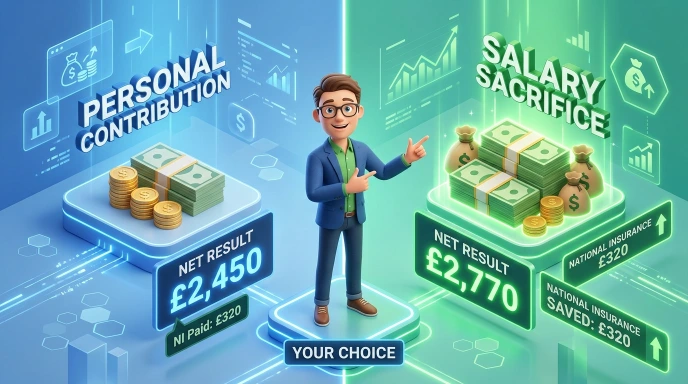
| Salary sacrifice | You agree to a lower official salary; employer pays the difference in | No — full relief is automatic, and you save National Insurance too |
The practical takeaway: if you’re on a net pay arrangement or salary sacrifice, you can largely stop worrying about “claiming” relief — it’s already baked in. If you’re on relief at source (common with many personal and some workplace pensions) and you pay tax above the basic rate, the claiming step genuinely matters. Check your payslip or ask your pensions team which one you’re on if you’re not sure — it’s the single biggest factor in whether this article applies to you directly.
Why This Matters More the More You Earn
Pension tax relief isn’t just a flat perk — it scales with your tax band, which means the financial case for contributing more gets stronger, not weaker, as your income rises. A £1,000 contribution “costs” a basic rate taxpayer £800 out of pocket. For a higher rate taxpayer claiming their full relief, that same £1,000 contribution can cost as little as £600. For someone caught in the Personal Allowance taper between £100,000 and £125,140 — where the effective marginal rate can reach around 60% — pension contributions become one of the few practical ways to bring your adjusted income back down and protect your allowance, on top of the relief itself.
None of this is a reason to contribute more than you can comfortably afford. But it’s a reason to at least run the numbers before assuming pension contributions are a fixed, unchanging cost.
What’s the Pension Tax Relief Limit?
Relief isn’t unlimited. Two caps matter:
The Annual Allowance
£60,000 for 2026/27, or 100% of your UK earnings if lower — this is the total that can go in with relief, combining your contributions, your employer’s, and the relief itself. Go over it and you may face an extra tax charge.
Tapering for Very High Earners
If your adjusted income is above £260,000, your annual allowance shrinks — check your pension provider’s yearly statement, since the exact figure depends on your specific income.
For the vast majority of people, neither limit is close to being an issue — but if you’re a higher earner making large contributions, it’s worth checking before you assume every penny gets relief.
Common Mistakes People Make With Pension Tax Relief
- Assuming relief is always automatic. It’s automatic at 20%. Above that, in a relief-at-source scheme, it usually isn’t.
- Not knowing which contribution method they’re on. Relief-at-source, net pay, and salary sacrifice are handled completely differently — see our Salary Sacrifice vs Personal Pension Contributions guide for the full breakdown.
- Forgetting to declare contributions on Self Assessment, and simply losing the extra relief they were owed.
- Confusing tax relief with the annual allowance — they’re related, but they’re not the same thing.
Frequently Asked Questions
How do I get 40% tax relief on my pension? You automatically get 20% relief through your pension provider. To get the full 40% as a higher rate taxpayer, you need to declare your contributions through Self Assessment or by contacting HMRC directly — it isn’t added to your pension pot automatically in a relief-at-source scheme.
What’s an example of pension tax relief in practice? On a £4,400 contribution as a higher rate taxpayer, you’d get £880 automatically (20%) added by your provider, plus another £880 (20%) reclaimable through Self Assessment or HMRC — for £1,760 of relief in total.
Is there a limit on pension tax relief? Yes — the annual allowance, £60,000 for 2026/27 (or 100% of your earnings if lower), covers your contributions, your employer’s, and the relief combined. Very high earners may have a lower, tapered allowance.
Do I automatically get pension tax relief through salary sacrifice? Yes — with salary sacrifice, full relief is applied automatically through payroll at whatever rate you pay tax, with nothing to claim separately.
How do I know if I’m on relief at source, net pay, or salary sacrifice? Check your payslip or your pension scheme’s member documents — it’s usually stated outright. If your gross salary on your payslip is lower than your contractual salary in your employment offer, you’re likely on salary sacrifice.
How do I work out exactly how much relief applies to me? Use our UK Pension Tax Calculator — enter your salary and contribution percentage, and it shows your exact marginal rate and the pound amount of relief you’re entitled to.
This article is for general guidance only and does not constitute tax advice. Tax relief rules can vary based on individual circumstances — for anything beyond the general rules covered here, speak to HMRC or a qualified accountant. See our full disclaimer.