Written and fact-checked by Waseem Aijaz, WordPress Developer & SEO Expert.
Quick answer: For the same amount going into your pension, salary sacrifice usually leaves you with slightly more take-home pay than a personal contribution, because it also reduces the earnings your National Insurance is calculated on. A personal contribution only gets you Income Tax relief — salary sacrifice gets you both.
The Core Difference, in Plain English
Both methods put money into your pension. The difference is when it’s taken from your pay, and what it’s calculated against.
- Personal contribution (relief at source): You’re paid your full salary, National Insurance included. Your pension contribution comes out afterwards, and your provider tops it up with 20% tax relief automatically.
- Salary sacrifice: You formally agree to a lower contractual salary. Your employer pays the difference straight into your pension instead. Because your official salary is now lower, both your Income Tax and your National Insurance are calculated on that smaller number.
That second point is the entire reason salary sacrifice tends to win. Personal contributions only touch Income Tax. Salary sacrifice touches Income Tax and National Insurance.
Is Salary Sacrifice Actually Worth It? A Real Example
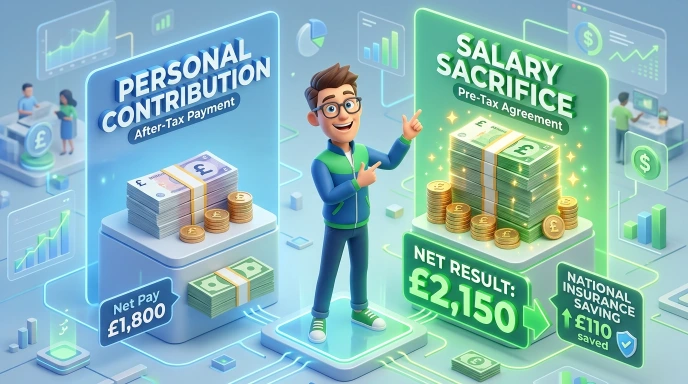
Let’s say you earn £45,000 and want to put 6% of your salary — £2,700 — into your pension.
With a Personal Contribution
You’re taxed and pay National Insurance on the full £45,000. Your £2,700 contribution gets topped up with basic rate relief, so it “costs” you roughly £2,160 net.
With Salary Sacrifice
Your contractual salary effectively drops to £42,300 for tax and National Insurance purposes. You pay less Income Tax and save 8% National Insurance on that £2,700 — around £216 extra, on top of the same tax relief you’d have gotten anyway.
Same £2,700 landing in your pension either way. But with salary sacrifice, your take-home pay ends up roughly £200+ higher over the year, purely from the National Insurance saving. That gap grows if you’re a higher rate taxpayer or contributing a bigger percentage.
When a Personal Contribution Might Still Make Sense
Salary sacrifice isn’t automatically right for everyone:
- Your employer has to offer it. Not all workplace pension schemes support salary sacrifice — plenty only offer relief-at-source personal contributions.
- It lowers your official salary, which can affect mortgage applications, some employer benefits, and statutory pay calculations (like maternity or sick pay) if they’re based on your contractual salary.
- If you’re close to the National Minimum Wage, your employer legally can’t let your salary drop below it through sacrifice — there are built-in limits.
- Some people simply prefer the flexibility of adjusting a personal contribution up or down without changing their formal salary.
If any of those apply to you, it’s worth having a specific conversation with HR before assuming salary sacrifice is automatically the better move.
Side-by-Side: £45,000 Salary, 6% Contribution
| Personal Contribution | Salary Sacrifice | |
|---|---|---|
| Contribution amount | £2,700 | £2,700 |
| Income Tax relief | Automatic, 20% | Automatic, at your rate |
| National Insurance saved | None | Yes — on the sacrificed amount |
| Approximate extra take-home pay | — | ~£200+/year higher |
| Affects contractual salary shown on payslip | No | Yes |
| Requires employer to offer it | No | Yes |
Numbers will shift depending on your exact salary, tax band, and contribution percentage — which is exactly why a flat “salary sacrifice is always better” answer isn’t quite honest. Run your own figures rather than relying on someone else’s example.
What If You’re Also Repaying a Student Loan?
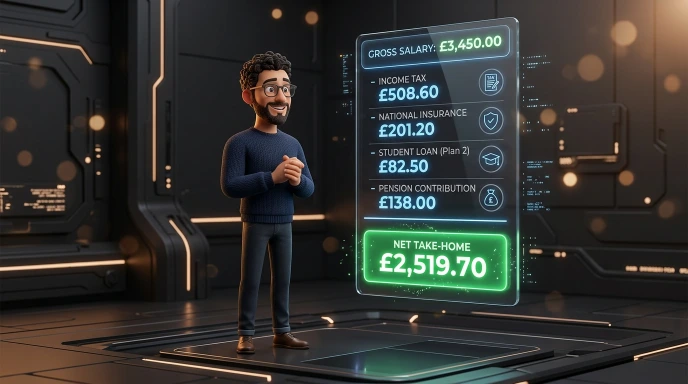
This is where salary sacrifice can help even more, and it’s a detail a lot of comparisons miss entirely. Student Loan repayments are calculated on your gross earnings above your plan’s threshold — so a lower official salary through salary sacrifice can also reduce your student loan repayment, on top of the tax and National Insurance savings. It’s not a reason on its own to choose salary sacrifice, but it’s a real, extra factor worth knowing about if it applies to you.
How to Ask Your Employer About Salary Sacrifice
- Check your current payslip or pension scheme documents to see which method you’re already on.
- Ask HR or your pensions team directly whether salary sacrifice is available — some schemes offer it as an opt-in, not the default.
- Confirm how it affects anything tied to your contractual salary — mortgage references, life insurance multiples, and maternity/paternity pay calculations are the ones people forget to check.
- Compare both methods on your real salary before deciding, rather than going on a rule of thumb.
Does Salary Sacrifice Change What Your Employer Contributes?
Sometimes, and it’s worth asking about directly. Some employers pass their own National Insurance saving (employer NI is currently 15% on earnings above the secondary threshold) back into your pension on top of what you sacrifice — effectively boosting your contribution further at no extra cost to you. Others simply keep that saving. Neither is universal, so it’s a fair, direct question to put to HR: “If I move to salary sacrifice, do you pass on your employer National Insurance saving into my pension?” The answer changes the maths meaningfully in your favour if it’s yes.
The Long-Term Effect of a Small Yearly Difference
A £200-a-year difference in take-home pay, or an equivalent amount landing in your pension instead, doesn’t sound dramatic on its own. But pension contributions aren’t a one-off — they’re typically a decision you make every year, for decades. Money inside a pension is also invested and grows over time, so a consistently larger contribution, even a modest one, compounds. This isn’t a promise of any specific return — investment growth is never guaranteed and depends entirely on your pension’s funds and the markets — but the structural point holds regardless of performance: whichever method leaves slightly more going into your pension each year, rather than sitting in a current account, tends to matter more the earlier it starts.
Common Mistakes When Comparing the Two
- Assuming the percentage contribution “costs” the same either way. It doesn’t — the National Insurance saving under salary sacrifice makes the real-world cost slightly lower for an identical pension contribution.
- Not checking whether salary sacrifice affects mortgage affordability calculations. Lenders generally use your post-sacrifice salary, which can matter if you’re applying for a mortgage soon — worth timing the conversation with your lender in mind.
- Forgetting to ask if the employer passes on their own National Insurance saving. It’s optional on the employer’s side, and easy to miss if you don’t ask directly.
- Switching methods without checking the effect on statutory pay. Maternity, paternity and sick pay calculations can be based on your official salary — confirm this with HR before making a change if it’s relevant to you.
Frequently Asked Questions
Is salary sacrifice always better than a personal pension contribution? For most people, it leaves slightly more take-home pay for the same pension contribution, because it also saves National Insurance. It isn’t guaranteed to suit everyone — check whether it affects your contractual salary in ways that matter to you, like mortgage applications.
How does salary sacrifice work for a pension, exactly? You agree to a lower contractual salary, and your employer pays the difference straight into your pension. Both your Income Tax and National Insurance are then calculated on the reduced salary, rather than your original one.
Does salary sacrifice affect my take-home pay in a bad way? No — your take-home pay is usually slightly higher than with an equivalent personal contribution, not lower, because of the National Insurance saving.
Can I choose how much to sacrifice? Usually yes, as a percentage or fixed amount, though your employer must keep your official salary at or above the National Minimum Wage.
Where can I compare both methods using my own salary? Our UK Pension Tax Calculator has a built-in “Compare Personal vs Salary Sacrifice” view that shows the exact difference for your salary and contribution percentage — including the effect on Student Loan repayments if that applies to you. For how the tax relief itself is calculated either way, see our Pension Tax Relief Explained guide.
This article is for general guidance only and does not constitute financial advice. Whether salary sacrifice suits you depends on your personal circumstances — speak to your employer’s HR team or a financial adviser before making changes. See our full disclaimer.