Quick Answer
The most common first time homebuyer mistakes are skipping the home inspection, not getting pre-approved before house hunting, underestimating closing costs, and waiving contingencies to win a bidding war. Each one can cost thousands of dollars — this guide walks through how to avoid all of them.
Introduction
Buying your first home is exciting enough to make you skip steps you’d never skip on a smaller purchase. I get it — after months of searching, it’s tempting to move fast once you find “the one.”
But a few rushed decisions early on are exactly where first-time buyers lose the most money, sometimes without realizing it until months after closing. Here’s what to watch for, based on the mistakes that come up again and again.
The Biggest First Time Homebuyer Mistakes, One by One
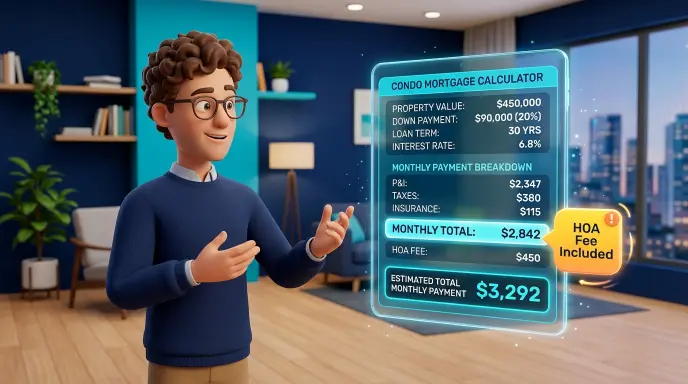
1. Skipping the Home Inspection
In competitive markets, some buyers waive inspections to make their offer more appealing. This can backfire badly — a skipped inspection means you inherit every hidden problem, from foundation cracks to outdated wiring, with no way to negotiate repairs or walk away once you’ve discovered them.
What to do instead: If you’re in a competitive bid, consider a pre-inspection before making your offer, or at minimum keep an inspection contingency with a short timeline so you’re not slowing down the process while still protecting yourself.
2. House Hunting Before Getting Pre-Approved
Touring homes without a pre-approval letter wastes time and can lead to heartbreak if you fall for a place outside your real budget. Pre-approval also makes your offer more competitive once you find the right property, since sellers take unverified buyers less seriously.
3. Underestimating Closing Costs
Closing costs typically run 2-5% of the purchase price, covering things like the appraisal, title insurance, loan origination fees, and prepaid property tax and insurance. Buyers who budget only for the down payment are often caught off guard here, sometimes scrambling to cover the gap right before closing.
4. Waiving Every Contingency to Win a Bid
An appraisal gap contingency, a financing contingency, an inspection contingency — waiving all of them might make your offer stand out, but it also removes your safety net if something goes wrong before closing. If the appraisal comes in low and you’ve waived that contingency, you could be on the hook for the difference in cash.
5. Not Shopping Around for Mortgage Rates
Many first-time buyers accept the first rate they’re offered, often from whichever lender their agent recommends. Comparing loan estimates from a few lenders can meaningfully lower your rate and save thousands over the life of the loan — it typically only costs you a bit of time.
6. Forgetting About Ongoing Costs After Move-In
The excitement of closing can overshadow the reality of ongoing costs: utilities in a bigger space, HOA dues, lawn care, and the inevitable first-year repairs. Budgeting only for the purchase, not the year after, is a common gap.
Mistake Cost Comparison
| Mistake | Potential Cost Impact |
|---|---|
| Skipping inspection | $1,000s in unexpected repairs |
| Waiving appraisal contingency | Difference between offer and appraised value, in cash |
| Not comparing lenders | Thousands over the loan’s life from a higher rate |
| Underestimating closing costs | Scramble for 2-5% of purchase price at the last minute |
| Ignoring post-move-in costs | Strained monthly budget in year one |
Expert Insight: Read the Closing Disclosure Carefully
Your closing disclosure arrives a few days before closing and lists every final cost. It’s worth comparing it line by line against your original loan estimate — discrepancies happen, and catching them early can save you money or at least prevent an unpleasant surprise at the closing table. Federal rules give you a mandatory review period before signing specifically so you have time to check this.
Checklist to Avoid First Time Homebuyer Mistakes
- Get pre-approved before touring homes
- Never skip the home inspection, even in a competitive market
- Budget for closing costs, not just the down payment
- Keep at least an inspection and financing contingency in your offer
- Compare loan estimates from at least 2-3 lenders
- Review your closing disclosure line by line before signing
- Set aside a post-move-in buffer for unexpected repairs and setup costs
Pros and Cons of Moving Fast in a Competitive Market
Pros of moving quickly
- Stronger negotiating position on price
- Less likely to lose the home to another buyer
Cons of moving quickly
- Higher risk of skipping due diligence like inspections
- Less time to compare mortgage rates
- Pressure to waive protective contingencies
Run Your Numbers Before You Offer
Before you make an offer, it’s worth confirming buying actually beats renting for your specific timeline and budget — not just assuming it does because everyone says homeownership is a good investment. Our rent vs buy calculator shows your break-even year, including PMI and closing costs, so you’re deciding with real numbers instead of gut feeling.
Frequently Asked Questions
What is the biggest mistake first-time homebuyers make? Skipping the home inspection is one of the costliest, since it can hide expensive structural or system problems that surface only after you own the home and have no recourse against the seller.
How much should I budget for closing costs? Plan for roughly 2-5% of the purchase price, though this varies by state, lender, and loan type.
Should I waive contingencies to make my offer competitive? It’s risky. Waiving contingencies can make your offer stand out, but it removes protections that let you walk away or renegotiate if problems arise during the process.
Is it worth shopping around for mortgage rates as a first-time buyer? Yes — even a small rate difference can save thousands over a 30-year loan, so comparing at least a few lenders is worth the extra time it takes.
How long does the closing disclosure review period last? Federal rules generally require at least a three-business-day review period before closing, giving you time to catch any discrepancies against your original loan estimate.
Do I need a real estate agent as a first-time buyer? It’s not legally required, but an experienced agent can help you avoid several of the mistakes above, particularly around contingencies and local market norms.
Conclusion
Most first-time homebuyer mistakes come from moving too fast under pressure, whether that’s market pressure or just excitement about a new home. Slow down where it matters most — inspections, contingencies, and comparing lenders — and you’ll sidestep the costliest surprises. Once your offer numbers are set, double-check the full financial picture with our rent vs buy calculator before you sign anything.
This article is for informational purposes only and does not constitute financial or legal advice. Consult a licensed real estate professional or attorney for guidance specific to your situation.