By Waseem Aijaz, WordPress developer and SEO specialist. Last updated: October 12, 2026. Rates are national medians from NerdWallet’s October 2026 analysis.
Look, I want to make one thing clear. This content is only for informational purposes. It does not provide any advice. I create these tools by working with experts to solve problems that I or my clients have faced, so people can find a solution to their problems.
That is why I mention that you should use this tool only for informational purposes.
Quick answer: How much does car insurance go up after a speeding ticket? On average, about 28%. For a 35-year-old with good credit, full coverage rises from $2,361 to $3,028 a year, which is roughly $56 more a month. An at-fault accident adds about 49% (around $97 a month) and a DUI adds about 88% (around $173 a month). Your own increase will depend on your insurer, your state and the details of the violation.
The increase at a glance (full coverage, national median):
- Speeding ticket: +28%, or $667 more a year
- At-fault accident: +49%, or $1,163 more a year
- DUI: +88%, or $2,076 more a year
- Poor credit, clean record (for comparison): +67%, or $1,593 more a year
I’m a developer and SEO specialist, not an insurance agent. I built these numbers into a free tool so you can check them yourself, and every source is listed at the bottom.
How Much Does Car Insurance Go Up After a Speeding Ticket, Crash or DUI?
Nobody wants to open a renewal notice after a violation. So here are the actual numbers, starting with the baseline. NerdWallet’s October 2026 analysis prices a 35-year-old driver with good credit and a clean record at a national median of $2,361 a year for full coverage and $648 a year for minimum coverage. Every increase below is measured against that.
Speeding ticket
One speeding ticket moves the full-coverage median from $2,361 to $3,028 a year. That’s $667 more, or about $56 a month. On minimum coverage, the jump is smaller in dollars, from $648 to $840 (about $16 a month), but it’s a similar 30% in percentage terms.
The ticket in NerdWallet’s sample was for driving 16 mph over the limit. A smaller violation may cost less and a bigger one usually costs more, but each insurer has its own rules.
At-fault accident
An at-fault accident adds more. Full coverage goes from $2,361 to $3,524 a year. That’s $1,163 more, or about $97 a month. Minimum coverage goes from $648 to $952, about $25 a month extra.
The crash in the sample caused $10,000 in property damage and no injury claim. A bigger claim will often mean a bigger increase. Many insurers also treat a crash that wasn’t your fault differently, though not all do.
DUI
A DUI is the heaviest of the three. Full coverage jumps from $2,361 to $4,437 a year. That’s $2,076 more, or about $173 a month. Minimum coverage goes from $648 to $1,231, about $49 a month extra.
In many states a DUI also means your insurer has to file an SR-22 with the state. It’s a certificate that proves you carry coverage. A few states use a similar form called an FR-44. Some insurers won’t write a policy after a DUI at all, so shopping around matters even more.
The surprise: poor credit can cost more than a crash
With a clean record, poor credit adds about 67%, taking full coverage to $3,954 a year. That’s more than an at-fault accident (+49%). Credit is used in most states, though California, Hawaii and Massachusetts, for example, don’t allow it. If you’ve been worrying only about your driving record, this is worth knowing.
National Costs by Driving Record, Side by Side
| Driver profile | Full coverage a year | Change | Extra a month | Minimum coverage a year | Change |
|---|---|---|---|---|---|
| Clean record, good credit | $2,361 | Baseline | Baseline | $648 | Baseline |
| One speeding ticket | $3,028 | +28% | +$56 | $840 | +30% |
| One at-fault accident | $3,524 | +49% | +$97 | $952 | +47% |
| One DUI | $4,437 | +88% | +$173 | $1,231 | +90% |
| Clean record, poor credit | $3,954 | +67% | +$133 | $1,030 | +59% |
Source: NerdWallet’s October 2026 rates analysis. Rates are for a 35-year-old driver, and each violation in the sample was six months old.
Real Examples: What the Increase Looks Like in Dollars
A percentage means different things in different places. Here’s the same 28%, 49% and 88% applied to two cities from The Zebra’s October 2026 table. These are full coverage, age 30 to 59.
| Record | Chicago | Raleigh |
|---|---|---|
| Clean | $3,030 a year ($253 a month) | $1,328 a year ($111 a month) |
| One speeding ticket | $3,886 ($324) | $1,703 ($142) |
| One at-fault accident | $4,523 ($377) | $1,982 ($165) |
| One DUI | $5,695 ($475) | $2,496 ($208) |
The same ticket adds about $856 a year in Chicago and about $375 in Raleigh. A percentage applied to a bigger base is a bigger bill.
Age stacks on top, too. For a Houston driver aged 20 to 29, our estimator puts a clean record at about $4,194 a year and one speeding ticket at about $5,380, a difference of roughly $1,185. These are point estimates. The tool shows a range of plus or minus 20%, because real insurers differ that much.
Want your own numbers? Try the car insurance calculator without personal information. Pick your city, age, driving record and coverage, and you get a monthly and yearly range without typing your name, email or VIN.
Why the Increase Is Different for Every Driver
Two drivers with the same ticket can see very different renewals. Here’s why:
- Your insurer. Each company weighs violations in its own way. In NerdWallet’s October 2026 comparison, eight insurers priced one identical clean-record driver in a sample ZIP code from $75 to $171 a month.
- Your state. Rules, minimum coverage levels and base rates differ a lot. See the average car insurance cost by state for the full picture.
- How serious the violation was. Speed over the limit, injuries and claim size all matter.
- Your history. A long clean record before the ticket helps. A second violation hurts more than the first.
- Your age and credit. Both change the base rate that the surcharge is applied to.
How Long Does a Ticket or Accident Affect Your Insurance?
The honest answer is that it depends on your state and your insurer. As a rough guide, many insurers look back about three years for a speeding ticket. An at-fault accident is often considered for three to five years, and a DUI can follow you for five years or longer. Some states and insurers look back further.
Treat those as typical ranges, not rules. Ask your insurer how far back it looks, or check with your state’s department of insurance. Your price should also ease as the violation ages, which is why re-shopping each year pays off.
How to Lower Your Rate After a Ticket, Accident or DUI
Eight moves that help
- Shop right away, then again every year. Get at least three quotes for the same coverage. Since insurers weigh violations differently, the gap between them can be bigger than the surcharge itself.
- Ask what’s still discountable. Bundling, low mileage and safe-driver programs may still apply.
- Ask about a defensive driving course. Some insurers give a discount, and in some places a court may offer traffic school instead of points. Rules differ, so ask first.
- Look at your options on the ticket. If it’s reasonable, speak to the court about what’s possible before you just pay.
- Raise your deductible, but only to an amount you could pay tomorrow.
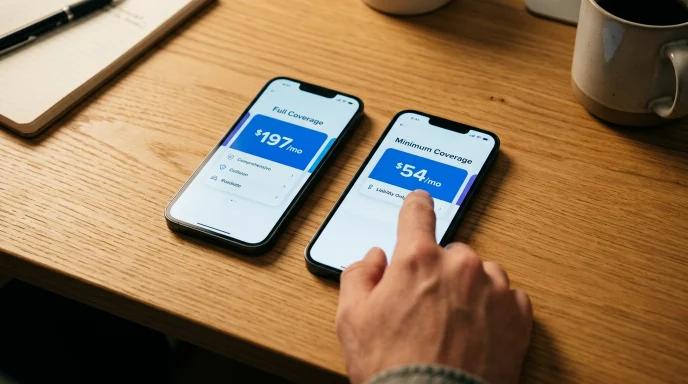
- Don’t drop to minimum coverage just to offset the surcharge. If you finance the car, your lender will usually require full coverage anyway. You can model the payment in Loan Analytics Pro.
- Work on your credit. Poor credit can cost more than a ticket in most states.
- Give it time. As the violation ages, your price should come down.
Budget for the new number, too. The Income Tax Calculator 2026 shows your take-home pay, so you can see where an extra $56 to $173 a month fits.
Common mistakes after a violation
- Staying with the same insurer out of habit. Loyalty rarely beats a quote comparison.
- Comparing quotes with different coverage. A cheaper quote may simply cover less.
- Leaving a violation off an application. Insurers check driving records, and a misstatement can cause trouble later.
- Assuming the increase is permanent. It usually fades with time.
Quick checklist
- I know my base rate before the violation
- I’ve estimated the increase with a range, not one number
- I’ve asked my insurer how long the violation counts
- I’ve got three quotes for the same coverage
- I’ve asked about discounts and a defensive driving course
Frequently Asked Questions
How much does car insurance go up after a speeding ticket?
By about 28% on average. For a 35-year-old with good credit, full coverage rises from $2,361 to $3,028 a year, about $56 more a month. Minimum coverage rises about 30%, from $648 to $840. Your own increase depends on your insurer, state and how fast you were going.
Will one speeding ticket raise my insurance?
Usually, yes, but not always. Some insurers don’t surcharge a minor first violation, and some offer forgiveness programs. Because every company is different, ask your insurer and compare quotes after the ticket.
How much does car insurance go up after an at-fault accident?
About 49% on average. Full coverage goes from $2,361 to $3,524 a year, roughly $97 more a month. Minimum coverage goes up about 47%.
How much does car insurance go up after a DUI?
About 88% on average for full coverage, from $2,361 to $4,437 a year, roughly $173 more a month. Minimum coverage rises about 90%. Many states also require an SR-22, and some insurers won’t cover you at all.
How long does a speeding ticket affect your car insurance?
Often about three years, but it varies by state and insurer. Ask your insurer how far back it looks, and keep re-shopping each year as the ticket ages.
Is poor credit worse than a speeding ticket for car insurance?
In most states, yes. Poor credit with a clean record adds about 67% to full coverage, while a speeding ticket adds about 28%. A few states, such as California, Hawaii and Massachusetts, don’t let insurers use credit.
Can I see how much my insurance will go up without giving my details?
Yes. Use the free calculator and pick a driving record. It shows a monthly and yearly range for your city or state, with no name, email or VIN.
Conclusion
So, how much does car insurance go up after a speeding ticket? About 28% on average, with a crash adding about 49% and a DUI about 88%. In dollars that’s roughly $56, $97 and $173 more a month on full coverage. The real number for you depends on your insurer and where you live.
The best next step is simple. Get your own range from the calculator, then compare three real quotes. For more free money tools, browse our Finance Tools.
Sources (checked October 2026): NerdWallet for the national driving-record medians and The Zebra for city rates. Look-back periods are typical ranges and vary by state and insurer. This page gives general information, not an insurance quote or financial advice. See our disclaimer.